Available when houses actually sell
Showings at 7 PM, offer deadlines on Sunday, a "can we afford this one?" from the driveway — Ashland answers when the question happens, not Monday morning.
Buying & refinancing · MN, WI & IA
Every home buying and refinancing question, answered in plain English by a lender who has done this since 2016. Your agent finds the house; Ashland Alitz makes the financing land — straight answers on Saturday night, a payment on any listing in minutes, and a call to the listing agent with every offer.
Ashland · Lending Lakes & Co
usually replies in minutes
7
Days a week you can reach Ashland — nights and weekends included
10 min
For updated payment + cash-to-close math on offer day
1 call
To the listing agent with every offer you submit
1–2 days
Typical pre-approval turnaround once your documents are in*
* Timing varies by file and depends on receiving complete documentation. Turnaround figures are typical, not guaranteed. This is not an offer to enter into an agreement; not all customers will qualify. Rates, programs and terms are subject to change. All loans subject to credit and property approval.
Why "realtor-centric" matters
Houses sell on Saturday nights and offer deadlines land at 5 PM Sunday. If your financing can't keep pace with your agent, you lose houses you could have won. Ashland built her whole process around that one fact.
Showings at 7 PM, offer deadlines on Sunday, a "can we afford this one?" from the driveway — Ashland answers when the question happens, not Monday morning.
Seller credits, appraisal gaps, contingency language, closing dates — Ashland works through the money side with your agent so the offer is built right the first time.
A personal call vouching for your financing, with Ashland's cell number attached. It answers the one question every listing agent has: will this actually close?
How Ashland helps
Most buyers think a lender's job is a rate. The rate is table stakes. The job is everything that happens between "we like this house" and the keys — and doing it fast enough that you win the house.
Income, assets and credit actually reviewed — then a letter written to match your offer, not your max. Usually a day or two once your documents are in.
Text Ashland an address and a price. Principal, interest, taxes, insurance, mortgage insurance and cash to close come back in minutes.
Updated numbers, a matched letter, and a personal call to the listing agent with every offer you submit — the quiet advantage in a multiple-offer weekend.
Your agent finds the house. Ashland makes the financing land. They talk to each other, so you never play phone tag between them.
Minnesota Housing, WHEDA in Wisconsin, the Iowa Finance Authority in Iowa. If assistance fits your file, Ashland pairs it with the right first mortgage — in whichever state you are buying.
Clear next steps at every milestone, straight answers to every question, and a process that runs quietly until the keys. Years later, when the refinance question comes up, the same honest math.
The question everyone actually has
Not the loan payment — the whole payment. Principal, interest, property taxes, homeowners insurance, mortgage insurance, HOA if there is one. The calculator shows all of it, instantly, with no sign-up. Then text Ashland the address for numbers specific to that house.
Run my numbers →Ashland · Branch Sales Manager & Loan Officer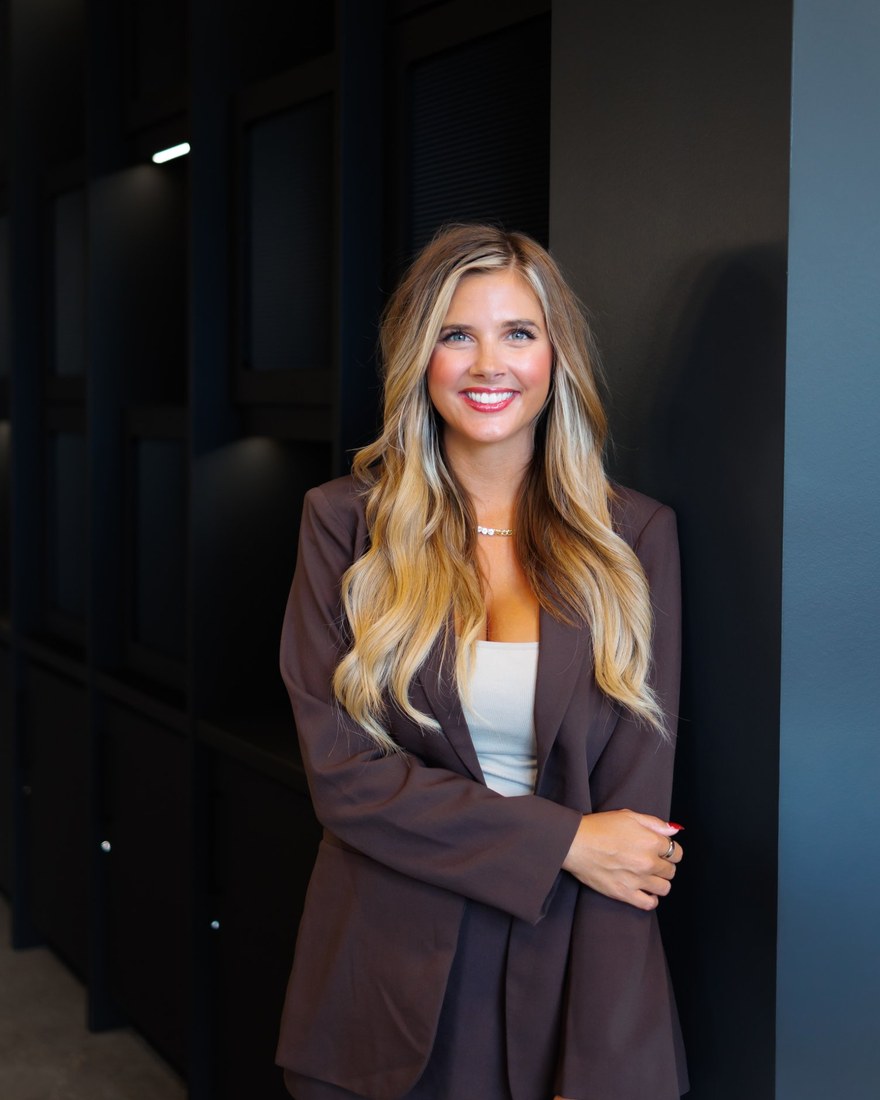
Meet Ashland
Ashland Alitz has originated loans since 2016 and built Lending Lakes & Co for the buyers the industry overlooks — first-time buyers, single buyers on one income, anyone told to come back when they've saved more. Three rules on every file: plain English, honesty over deals, and speed as respect.
Branch Sales Manager and Loan Officer with Fairway Home Mortgage in Eden Prairie, licensed in Minnesota, Wisconsin and Iowa, a 2025 HousingWire Rising Star and Scotsman Guide Top Originator — and the lender your real estate agent wants on the team.
Buyer & refinance guides
The single most expensive myth in home buying — and what buyers in Minnesota, Wisconsin and Iowa actually put down.
4 min read →07Rate-and-term, cash-out, dropping FHA mortgage insurance — and the one piece of math that decides all of them.
5 min read →08Single buyers and one-income households qualify every day. Here is how lenders actually look at it — and the programs built for you.
4 min read →Loan programs
The workhorse of home financing — flexible terms, competitive costs, and down payments as low as 3% for first-time buyers.
Learn more →The first-time buyer favorite — 3.5% down, friendlier credit requirements, and forgiving guidelines for real-life finances.
Learn more →For those who served — $0 down, no monthly mortgage insurance, and some of the strongest terms in all of lending.
Learn more →$0 down for homes in eligible smaller communities across Minnesota, Wisconsin and Iowa — far more towns qualify than buyers expect.
Learn more →Financing above conforming loan limits for higher-priced homes — with the same guidance and straight answers.
Learn more →Minnesota, Wisconsin and Iowa all have real down payment help — Minnesota Housing, WHEDA and Iowa Finance Authority programs can put thousands toward your down payment and closing costs.
Learn more →Lower the payment, drop mortgage insurance, tap equity, or shorten the term — when the math works, Ashland will show you. When it doesn’t, she’ll tell you.
Learn more →Perfect. That is a ten-minute conversation, not homework. Text Ashland what you are wondering about.
Text 612-505-7663 →Ready when you are
No dumb questions, no pressure, no forms to fill out. Text Ashland what you are wondering about and get a straight answer — usually the same day, nights and weekends included.
Applications happen on Fairway's secure site — never here.